Are Online Mortgage Rates Accurate for Castle Rock Buyers?
Are Online Mortgage Rates Accurate for Castle Rock Buyers?
Read the complete blog post below.
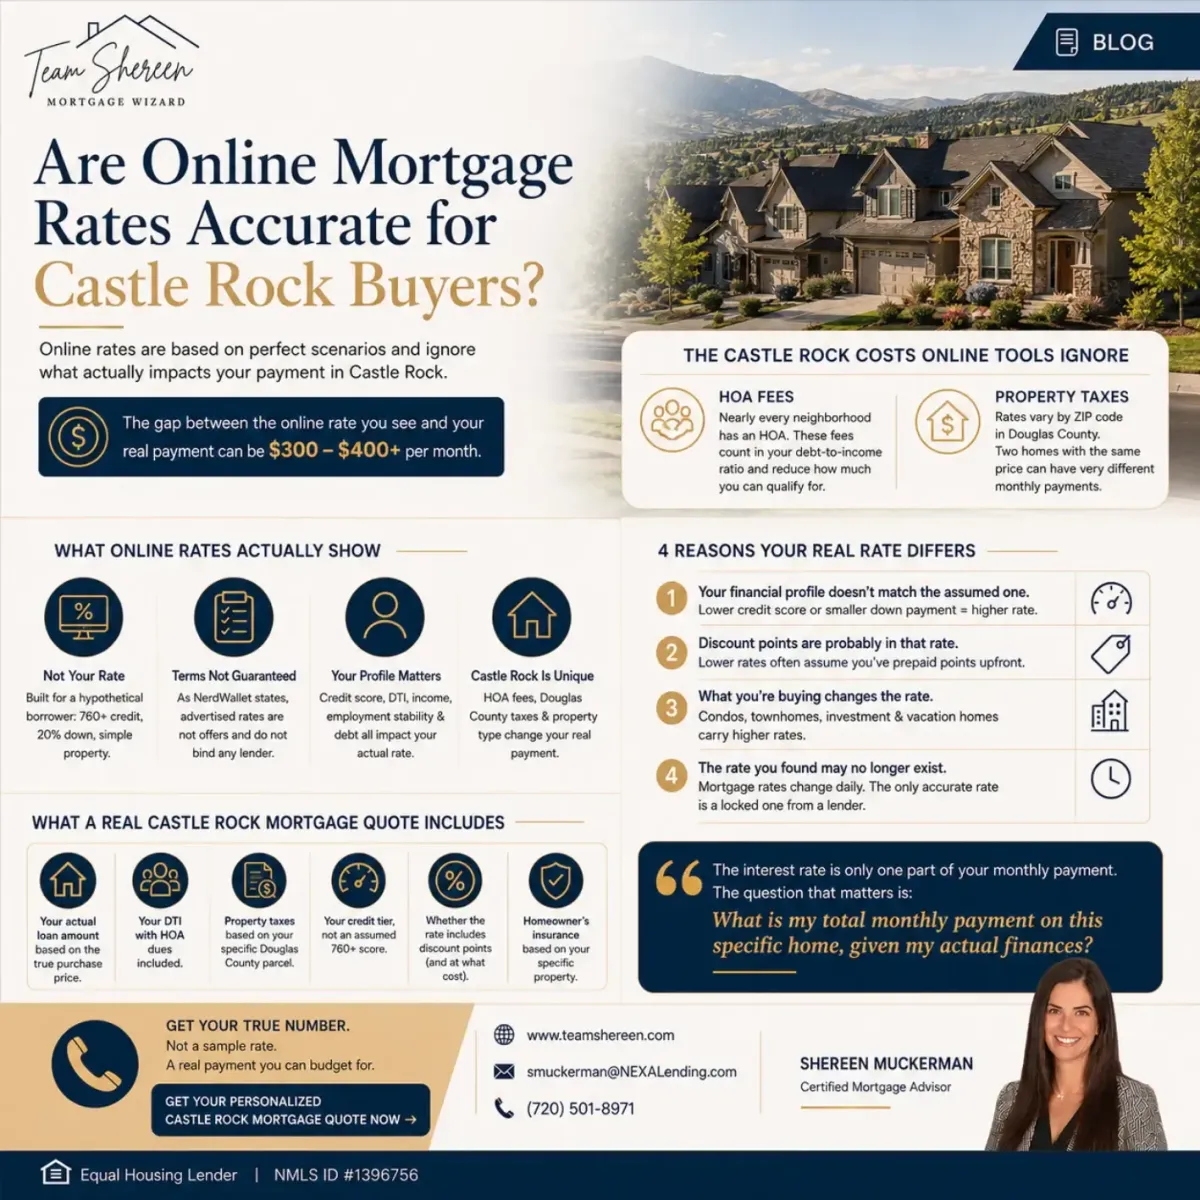
Here’s the truth: the mortgage rate you found online wasn't calculated for you. It was actually built for a borrower with perfect credit, 20% down, and a straightforward property, and it ignores everything that makes Castle Rock its own mortgage market.
HOA fees, Douglas County property taxes, your actual credit score, discount points hidden in the headline rate- these are the factors that determine what you'll really pay each month. And the gap between the online mortgage rate you saw and your real payment can easily reach $300 to $400 a month. Here's exactly why those advertised rates fall short, and what you need to ask an expert lender like Shereen Muckerman before you go any further.
What Online Mortgage Rates Actually Show You?
When you check an online mortgage rate on Bankrate or NerdWallet, you are not seeing your rate. You're seeing a rate designed for a hypothetical borrower who doesn't exist: 760+ FICO score, 20% down payment, buying a single-family primary residence, with no mention of whether discount points are baked in.
As NerdWallet states directly on its rates page, the terms advertised are not offers and do not bind any lender; your actual rate and loan terms are determined by the lender's assessment of your creditworthiness and other factors. When the best mortgage lender, like Shereen Muckerman, evaluates your application, they assess the following:
Credit Score & History: Lenders examine your credit reports to gauge repayment reliability.
Debt-to-Income (DTI) Ratio: This compares your monthly debt payments against your gross income.
Income & Employment Stability: A secure, steady income demonstrates the ability to comfortably afford the loan.
4 Reasons Your Real Rate Differs from What You Saw Online
1. Your Financial Profile Doesn't Match the Assumed One
Advertised rates are built around an ideal borrower. If your FICO score is 680 instead of 760, your rate increases. If your down payment is 10% instead of 20%, your rate increases again. Neither of those things is unusual. In 2025, the typical first-time buyer put down 10%.
Every element of your file- employment history, monthly debt obligations, and savings reserves- goes into the lender's risk pricing. An online rate tool sees none of it. This is one of the core reasons online mortgage rate accuracy in Castle Rock breaks down the moment a real borrower applies.
2. Discount Points Are Probably Already in That Rate
This is the one most buyers miss entirely.
When lenders quote an attractive rate, they often assume you've prepaid discount points at closing to buy the rate down. Each point costs 1% of the loan amount and typically lowers your rate by 0.25 percentage points. On a $650,000 Castle Rock home with 10% down, one point costs $5,850 upfront.
The rate you saw online may be that low only because it assumes you're paying thousands at closing to get there. That assumption never appears in the headline number. It shows up at the closing table. Discount points in Colorado mortgage quotes are among the least disclosed variables in rate advertising. Always ask any lender: Is this rate with or without points?
3. What You're Buying Changes the Rate
Investment properties and vacation homes carry higher rates because they represent higher default risk. But it goes further than that. Condos, townhomes, and homes within certain planned communities are priced differently by lenders than standalone single-family homes, and a significant portion of Castle Rock's inventory falls into these categories.
If the property you're targeting is a townhome in Terrain or a condo near Founders Parkway, the rate benchmarks you found online for single-family homes don't apply. Property type is one of the Castle Rock mortgage rate factors that comparison tools are structurally unable to account for.
4. The Rate You Found May No Longer Exist
Mortgage rates move continuously in response to bond markets, Federal Reserve policy, and economic data releases. The rate posted Monday morning can be gone by Monday afternoon. The most accurate rate you can get is a locked rate from a lender who has pulled your full credit profile and reviewed your target property. Everything before that is a benchmark.
The Castle Rock Costs That Online Calculators Ignore
This is where the real budget surprise lives for most Castle Rock buyers. The interest rate is only one part of your monthly payment. Two costs that online tools routinely undercount — or ignore entirely- can shift your payment by hundreds of dollars.
HOA Fees: The Hidden DTI Variable
Castle Rock is one of the most extensively master-planned communities in Colorado. Nearly every neighborhood has an HOA. Those fees are not optional, and lenders count them as a monthly debt obligation when calculating your debt-to-income ratio.
What does that mean in practice? Every dollar of HOA dues reduces the mortgage you can qualify for. The Colorado HOA mortgage impact is direct and mathematical; it's not an approximation.
HOA costs vary widely by neighborhood. But an online mortgage calculator has no idea which neighborhood you're targeting. It cannot tell you whether your HOA is $70 or $820. That gap can shift your qualified loan amount by tens of thousands of dollars, while the interest rate stays identical.
When you're evaluating any Castle Rock home, pull the full HOA financials, not just the current dues. Ask whether there are pending special assessments or known reserve shortfalls. That's what determines your real long-term cost.
Property Taxes: ZIP Code Matters More Than You Think
The Colorado property tax mortgage payment calculation is another area where online tools fall short, especially in Douglas County.
Castle Rock's median effective property tax rate is 0.63%, based on Douglas County property records. That number sounds small. On a $660,000 home, it adds roughly $347 per month to your payment, and that amount does not appear anywhere in the online mortgage rate you found.
More importantly, the rate isn't uniform across the city. The 80108 ZIP code carries a median effective rate of 0.68%, while 80104 runs 0.51%. Two homes with identical purchase prices in different Castle Rock ZIP codes carry different monthly payments. Mill levy variations by school district and local taxing authority create additional differences, sometimes between homes on the same street.
A lender using a national average property tax estimate will give you a payment that doesn't reflect reality in Douglas County.
What does a Real Castle Rock Mortgage Quote include?
If a lender gives you a rate without accounting for the following, you don't have a real Castle Rock mortgage rate quote yet. You have a starting point:
Your actual loan amount is based on the true Castle Rock purchase price, not a national median.
Your DTI with HOA dues included; the lender is required to count these. If they haven't asked about HOA dues, they haven't done the math.
Property taxes based on your specific Douglas County parcel, not a national or state average.
Your credit tier, not an assumed 760+ score; the rate tiers between FICO bands can be substantial.
Whether the rate includes discount points, and if so, the cost of those points at your loan size.
Homeowner's insurance premiums in Colorado have risen meaningfully in areas with wildfire risk exposure, which affects parts of the Douglas County market.
When a lender builds your quote with all of these in place and delivers it as a Loan Estimate, that is the only document that legally obligates them to your rate and fees. Until then, it's an approximation.
If you're still working through the basics of the mortgage process, Shereen Muckerman’s mortgage consultation session on getting pre-approved in Douglas County walks through exactly what lenders will ask for and why. If you're comparing loan types, our breakdown of conventional vs. FHA loans for Colorado buyers covers how each affects your rate and down payment requirements.
The Right Question to Ask
Most buyers focus on finding the lowest rate. That's the wrong goal.
Two Castle Rock buyers with identical interest rates can have monthly payments that differ by $400 or more, because of HOA structure, property tax districts, insurance costs, and loan size. The real mortgage rate vs. the advertised rate comparison only tells part of the story. The rate is one variable in a multi-variable equation.
The question worth asking is: What is my total monthly payment on this specific home, given my actual financial profile? That's the number that determines whether you can afford the neighborhood you want, not the number on a rate aggregator.
Get a Rate Built Around Your Actual Situation
An online rate gives you a reference point. It cannot give you a payment you can actually budget around, not in a market where HOA fees vary by hundreds of dollars per month, and property taxes shift by ZIP code.
At NEXA Lending LLC, Shereen Muckerman works specifically with Castle Rock buyers. She accounts for your HOA, your tax district, your credit file, and your loan amount, so what she gives you is a real number, not a sample calculation built around someone else's financial profile.
Get Your Personalized Castle Rock Mortgage Quote Now
Frequently Asked Questions
Q1. Why aren't online mortgage rates accurate for Castle Rock buyers?
Online mortgage rate accuracy in Castle Rock breaks down because every advertised rate is built around a perfect borrower in a generic market. Castle Rock has higher purchase prices, HOA dues in nearly every neighborhood, and Douglas County property taxes that shift by ZIP code. None of that fits the assumptions behind what you see on a comparison site.
Q2. What's the difference between a real mortgage rate and an advertised rate?
An advertised rate is the best-case number for a fictional borrower. Your real mortgage rate is calculated after a lender, like Shereen Muckerman, reviews your actual credit score, loan amount, property type, and full debt picture, including Castle Rock-specific costs like HOA fees and your Douglas County tax escrow.
Q3. What should a Castle Rock mortgage rate quote in Colorado actually include?
A real mortgage rate quote in Colorado covers your actual loan amount, HOA dues, Douglas County property tax district, your true credit tier, homeowner's insurance, and whether discount points are included. If a lender hasn't asked about your HOA, they haven't built you a real number.
Q4. How does the Colorado HOA mortgage impact work?
Lenders count HOA dues as a monthly debt obligation in your debt-to-income ratio. In Colorado, that directly reduces the loan amount you qualify for. In Castle Rock specifically, HOA fees range from $70 to over $800 per month, a gap that can move your qualified loan amount by tens of thousands of dollars.
Q5. How do Colorado property taxes affect my monthly mortgage payment?
Colorado property taxes are collected through your monthly escrow, so they add to your payment every single month. In Castle Rock, the median effective rate adds roughly $347 per month on a $660,000 home, and that figure shifts by ZIP code. A lender using a national average will undercount your real Douglas County payment.
Q6. Are discount points already built into Colorado mortgage rates I see online?
Frequently, yes. Many advertised Colorado mortgage rates already assume you've paid discount points at closing to buy the rate down. Each point costs 1% of your loan amount. On a $650,000 Castle Rock home, that's $5,850 due at closing that never shows up in the headline rate. Always ask your lender: Is this rate with or without points?
Q7. Do I need pre-approval before searching for homes in Castle Rock?
Yes, and an online mortgage rate check is not a pre-approval. A real pre-approval, done by someone like Shereen Muckerman, accounts for all the Castle Rock mortgage rate factors that comparison tools ignore: your credit profile, HOA obligations, and your specific Douglas County tax district. In a market with limited inventory and homes selling near the asking price, pre-approval isn't optional.


