How Much House Can I Realistically Afford In Colorado
How Much House Can I Realistically Afford In
Buying a home in Castle Rock is a big milestone. However, the math behind it can feel overwhelming fast. Prices vary by neighborhood, county taxes shift your payment, and HOA fees sneak up on you. So before you fall in love with a listing, let's break down key factors that shape home affordability in Castle Rock, CO. This guide gives you real numbers, practical formulas, and local Castle Rock data to help you move forward with confidence.
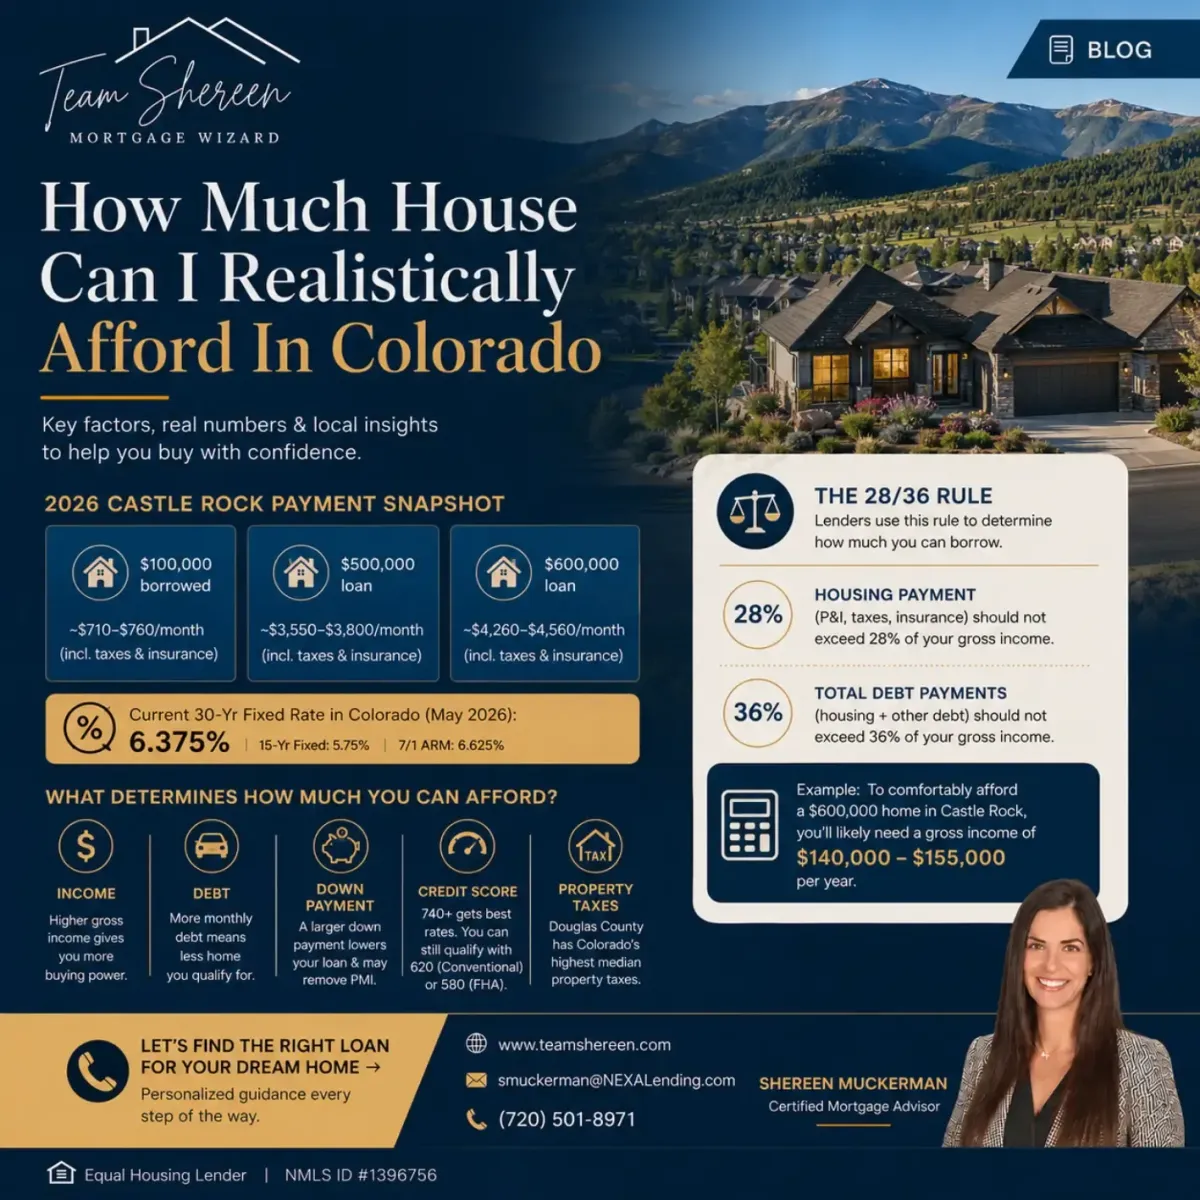
2026 Castle Rock Payment Snapshot
Castle Rock sits in Douglas County, one of Colorado's most popular and priciest suburbs. Homes in Castle Rock sold for a median price of $775,000 in April 2026, with properties sitting on the market an average of 46 days. That's a serious price point. Therefore, knowing your real monthly cost matters before you start shopping.
Here's a quick breakdown of what every $100,000 borrowed costs you in Castle Rock right now:
$100,000 borrowed: ~$710–$760/month (including taxes and insurance)
$500,000 loan: ~$3,550–$3,800/month
$600,000 loan: ~$4,260–$4,560/month
These numbers shift based on your interest rate, down payment, property taxes, and HOA fees. So let's look at each piece carefully.
Current mortgage rates in Colorado (2026):
As of May 2026, the 30-year fixed mortgage rate in Colorado sits at around 6.375%, the 15-year fixed rate is at 5.75%, and 7-year ARMs are coming in at 6.625%. As a result, your monthly payment on a $600,000 home with 10% down would be around $3,700–$3,900 before taxes and insurance.
What Determines How Much Home You Can Afford?
Your buying power depends on more than just your salary. Several factors work together to decide your real number. Let's walk through each one quickly.
Gross Monthly Income: Lenders look at your income before taxes. Therefore, a higher gross income gives you more room to borrow.
Monthly Debt Payments: Car payments, student loans, and credit card minimums all count. Consequently, the more debt you carry, the less home you qualify for.
Down Payment: A bigger down payment means a smaller loan. Moreover, it can help you avoid private mortgage insurance (PMI), which adds to your monthly cost.
Credit Score: A score above 740 gets you the best rates. However, you can still qualify with a score as low as 620 for a conventional loan or 580 for an FHA loan.
Property Taxes: This is where Colorado gets tricky. Your county makes a huge difference. Furthermore, even two homes with the same price can have very different monthly payments depending on their location.
Douglas County has the highest median annual property tax payment in Colorado at $4,548, which is $1,337 more than the national median of $3,211. Consequently, a $660,000 Castle Rock home carries a heavier tax load than a similar home in El Paso County.
Understanding the 28/36 Rule
Lenders use the 28/36 rule to decide how much you can borrow. Here's what that means in plain English:
28% rule: Your monthly housing payment (principal, interest, taxes, insurance) should not exceed 28% of your gross monthly income.
36% rule: Your total monthly debt payments (housing + all other debt) should not exceed 36% of your gross monthly income.
For instance, let's say you earn $120,000 per year. That's $10,000 per month.
28% of $10,000 = $2,800 max housing payment
36% of $10,000 = $3,600 max total debt payments
Now, with a 30-year mortgage at 6.375% and a $600,000 Castle Rock home, your principal and interest alone are around $3,380/month. Add taxes ($380/month) and insurance ($150/month), and your total is roughly $3,910/month. That's above the 28% threshold at a $120,000/year income.
Therefore, to comfortably afford a $600,000 home in Castle Rock, you'd likely need a gross income of at least $140,000–$155,000 per year.
For HOA-heavy neighborhoods like The Meadows or Crystal Valley Ranch, you need to push that number higher. Monthly HOA fees in Castle Rock range from $50 to $300 per month, depending on the community and amenities. As a result, add that to your total housing payment before comparing it to the 28% cap.
Real-Life Home Affordability in Castle Rock, CO: Examples
Let's put real numbers on a real-time scenario. This way, you can spot where you land:
If you borrow $360,000, the principal and interest payment is about $2,280 a month at 6.52%. Now add taxes and insurance. Then, the real payment rises. In Castle Rock, that can matter a lot because tax bills depend on the home and the district. Douglas County explains that property taxes are based on assessed value and mill levies, not just the sales price.
That means a monthly mortgage payment $450k Colorado buyers expect can look very different from one city to another. A $450,000 loan in a low-cost area may feel manageable. But the same loan in a higher-tax, HOA-heavy area can push the budget higher.
This is where Colorado gets tricky. The same purchase price can create different payments across the state. That is why buyers should study the whole payment, not only the sticker price.
Hidden Costs Many Colorado Buyers Forget
You've run the numbers on your loan. However, many buyers forget several costs that quietly add up every month. Here's what to watch for in Castle Rock and across the Denver metro.
1. Metro District Fees
Many newer Castle Rock neighborhoods sit inside metro districts. These are separate from HOA fees. Some master-planned communities charge HOA fees on top of property taxes, with budget estimates of $100–$200 per month for neighborhoods like The Meadows or Crystal Valley Ranch. Metro district fees can add another $50–$200/month on top of that.
2. Private Mortgage Insurance (PMI)
If you put down less than 20%, you'll pay PMI. This typically runs 0.5%–1.5% of your loan annually. For example, on a $500,000 loan, that's roughly $208–$625 per month. Therefore, consider how much PMI adds to your total payment.
3. HOA Special Assessments
HOAs in Colorado are facing rising insurance costs. In Castle Rock's Latigo community near Metzler Ranch, HOA fees shot from $300 to $820 per month in 2024 after insurance premiums jumped nearly 600%. As a result, always review an HOA's financials before you buy. Ask about reserve funds and any upcoming assessments.
4. Closing Costs
Colorado closing costs typically run 2%–4% of the purchase price. So on a $660,000 home, expect $13,200–$26,400 at closing. Plan for this separately from your down payment.
5. Maintenance and Repairs
Budget 1%–2% of your home's value per year for maintenance. On a $660,000 home, that's $6,600–$13,200 annually. Consequently, keep a cash reserve even after closing.
How Mortgage Loan Programs Affect Affordability?
Not all loans are created equal. The right loan program can make a big difference in what you can afford. Here are the main options available to Colorado buyers right now.
Conventional Loans:
The 30-year conventional mortgage rate in Colorado is around 6.125%–6.50%, with a credit score of at least 620 required. You can put down as little as 3%, though 20% avoids PMI. The 2026 conforming loan limit for most Colorado counties is $832,750. Therefore, most Castle Rock buyers can use a conventional loan without going jumbo.
FHA Loans
FHA loans help buyers with lower credit scores or smaller down payments. For 2026, FHA loan limits in Colorado range from $541,287 to $1,249,125, depending on the county. You only need 3.5% down, but you'll pay mortgage insurance for the life of the loan in most cases. FHA generally prefers a debt-to-income ratio at or below 43%.
VA Loans
If you're a veteran or active-duty service member, a VA loan is often the best deal. The VA 30-year fixed rate in Colorado comes in at around 6.11% APR. Furthermore, VA loans require no down payment at all. This makes them a powerful path to ownership in expensive markets like Castle Rock.
CHFA Programs (Colorado-Specific)
The Colorado Housing and Finance Authority offers down payment assistance. The CHFA Down Payment Assistance program offers up to $25,000 toward a purchase. This helps bridge the gap for first-time buyers who qualify. Ask your lender whether you meet the income limits for these programs.
Why Pre-Approval Is the Best First Step?
Many buyers browse homes before getting pre-approved. However, that approach wastes time and leads to disappointment. Pre-approval is the smartest move you can make before your first showing. Here's why.
First, it tells you your real number. A lender looks at your income, debt, credit, and assets. Then they give you a firm borrowing limit. Furthermore, this number is based on your actual situation, not a rough guess from a Castle Rock mortgage payment calculator.
Second, it makes sellers take you seriously. In Castle Rock, about 19.67% of homes were still sold above asking price in early 2026, with inventory at only 380 homes in March 2026. In a market that tight, sellers often choose offers backed by pre-approval letters. Consequently, showing up without one puts you at a real disadvantage.
Third, it speeds up closing. When you've done the income and credit work upfront, your loan closes faster. Moreover, a faster close can sometimes be the difference between winning and losing a home.
Final Verdict
Colorado's housing market rewards buyers who do their homework. Home Affordability in Castle Rock, CO, depends on five main things: your income, your debt load, your down payment, your loan program, and your county's taxes and HOA structure. The right combination of all five opens doors that feel out of reach today.
Ready to find out exactly what you can afford? Stop guessing. Start knowing.
At NEXA Lending LLC, Shereen Muckerman runs the real numbers with you, not just an online calculator. Shereen compares loan programs side by side so you see exactly where your dollar goes. She works with buyers across Castle Rock, Denver, and all of Colorado to match the right loan to the right lifestyle. Visit youwontbeatmyrate.com today and get your free pre-approval started, because your new home won't wait.
Frequently Asked Questions
Q: How much house can I afford in Castle Rock, CO?/
It depends on income, debt, down payment, tax bill, insurance, and HOA dues. Castle Rock prices also vary by area.
Q: What income do I need to buy a home in Castle Rock, CO?
To afford a median-priced Castle Rock home (around $660,000–$715,000), you generally need a gross annual income of $140,000–$170,000. However, your specific debt load, down payment, and loan program can shift that number up or down.
Q: What is the Douglas County property tax rate?
Douglas County carries the highest median annual property tax in Colorado at $4,548 per year. The effective Douglas County property tax rate runs around 0.76% of market value, though your exact bill depends on your home's assessed value and local mill levies.
Q: How does a Castle Rock mortgage payment calculator help for a $450k home in Colorado?
A Castle Rock mortgage payment calculator lets you plug in your loan amount, rate, taxes, and insurance to see your actual monthly payment. For a $450,000 home in Castle Rock, expect a total payment of roughly $2,900–$3,200/month, depending on your down payment and property location.
Q: Are there HOA neighborhoods in Denver and Castle Rock I should know about?
Yes. Popular HOA neighborhoods in Denver include The Meadows, Founders Village, Red Hawk Ridge, and Crystal Valley Ranch. HOA fees generally run $50–$300/month. In Cherry Creek and Central Denver, HOA costs can run higher, so factor them into your Home Affordability in Castle Rock, CO, math.
Q: What is mortgage affordability in 2026?
Mortgage affordability in 2026 refers to how much home you can comfortably afford based on your income, debts, mortgage rate, property taxes, insurance, and other monthly housing costs.
Q: What are Castle Rock home prices in 2026?
Castle Rock home prices remain strong in 2026, with values varying by neighborhood, home size, and market conditions. Buyers should review current local market data when planning their budget.


