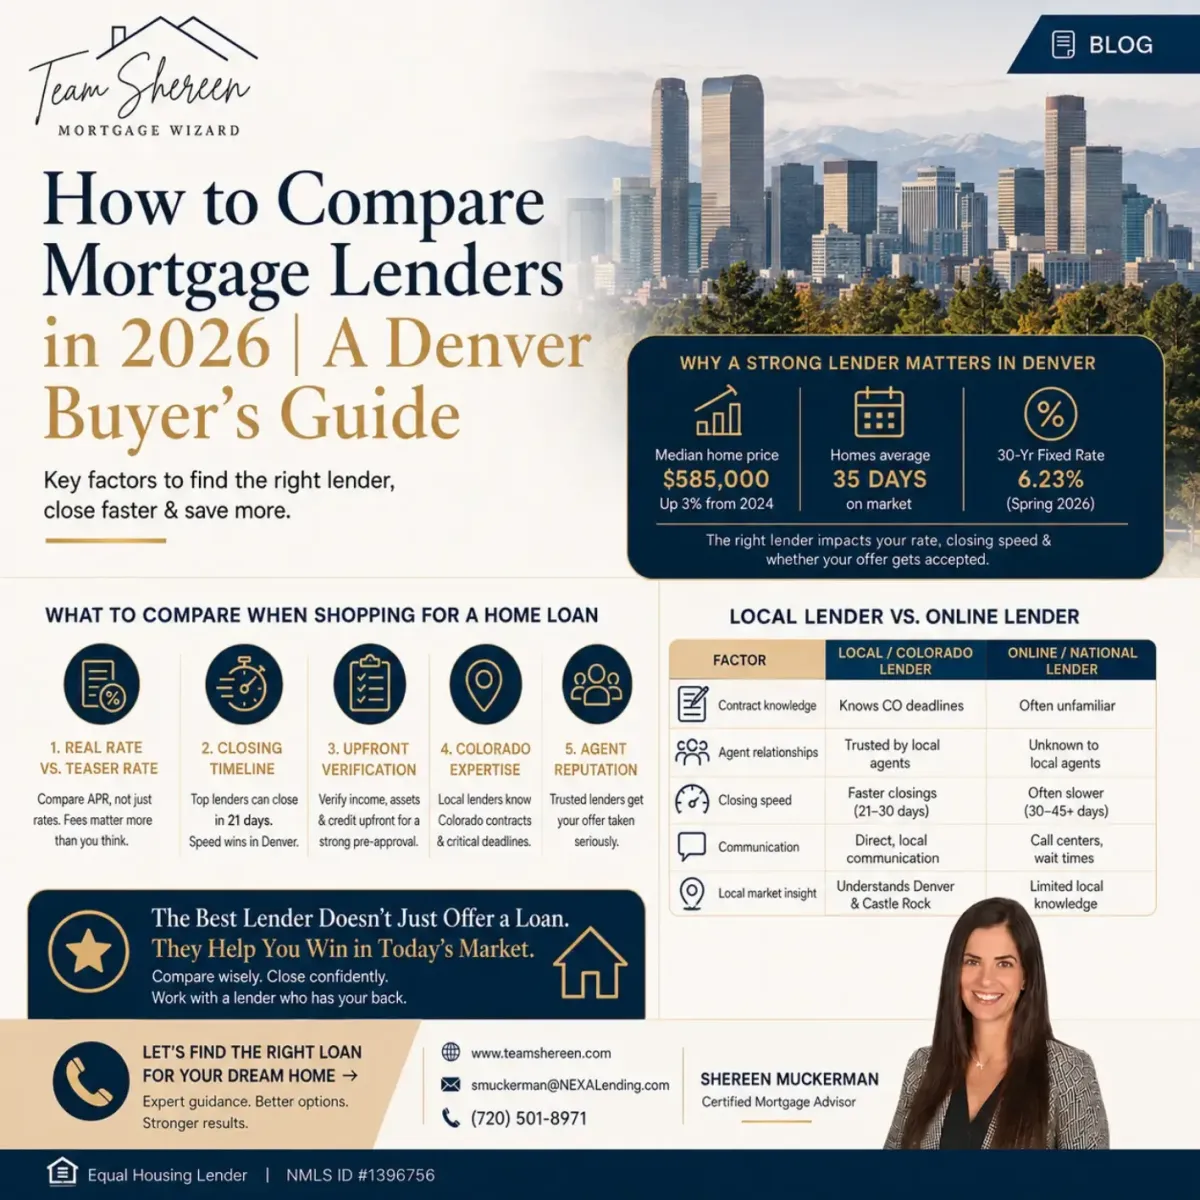
How to Compare Mortgage Lenders in 2026 | A Denver Buyer's Guide
Buying a home in Denver right now means more than finding the right property. It also means finding the right financing partner. The lender you choose shapes your rate, your closing speed, and your overall experience. Yet most buyers spend more time picking paint colors than picking a lender. That's a costly mistake.
This guide walks you through everything you need to know. You'll learn the key factors that separate average lenders from the best mortgage lender in Denver, CO. And we will show you why Shereen Muckerman is the best and strongest choice for a mortgage lender.
Why Does Denver Require a Strong Lender?
Denver's housing market in 2026 is not slowing down. According to DMAR's December 2025 Market Trends Report, the metro area continues to reward buyers who prepare well. Median home prices sit around $585,000, up 3% from 2024. Homes average 35 days on market. That pace leaves no room for lender delays.
Meanwhile, the 30-year fixed mortgage rate sits at 6.23% as of spring 2026 per Freddie Mac. Even a 0.25% rate difference on a $585,000 loan adds up to thousands of dollars over time. The mortgage lender you choose, such as Shereen Muckerman, can have a direct impact on that number.
There's also a competitive edge at play. Mortgage applications in Denver are up 10% year-over-year, according to early 2026 data. More buyers are active. That means sellers get more offers. Your lender's reputation and speed can decide whether your offer gets accepted or passed over. Clearly, this is not a decision to rush or ignore.
What to Actually Compare When You Shop for a Home Loan?
Most people stop at the interest rate. That is a mistake. Here is what you should actually be evaluating when you compare home loan options in the Denver area.
1. Real Rate vs. Teaser Rate
Some lenders advertise low rates. But look at the APR. The APR includes fees and gives you the true cost of the loan. A 6.25% rate with $4,000 in fees may cost more than a 6.35% rate with $500 in fees. As of June 17, 2026, the average 30-year fixed rate in Colorado sits at 6.34% APR. Any rate significantly lower should prompt questions about hidden fees.
2. Closing Timeline | Can They Actually Hit 21 Days?
This is the most critical factor in competitive Colorado markets. The standard Denver closing runs 30–45 days, but the fastest lenders can close in 21 days. Colorado loan commitment deadlines commonly run 21–30 days from contract acceptance, and 21 days is common in faster markets. Ask every lender: "What is your average closing time in Denver?" If they hedge, that is your answer.
3. Upfront Income Verification
A solid pre-approval is not just a letter. It means the lender has verified your income, assets, and credit before you make an offer. Weak pre-approvals fall apart during underwriting. This delays your closing or kills the deal entirely. Ask each lender: "Do you verify income upfront, or after the offer is accepted?"
4. Colorado Contract Knowledge
Colorado contracts have specific deadlines. Inspection objection periods. Title review windows. Loan commitment dates. A lender who does not know these timelines can miss critical deadlines. Local lending experts know the Colorado Real Estate Commission contracts inside and out. Out-of-state or purely online lenders often do not.
5. Reputation With Denver and Castle Rock Agents
Listing agents talk. They know which lenders close on time. They know which lenders create headaches.
When a Castle Rock listing agent sees a pre-approval from a trusted local lender, they feel confident recommending that offer to their seller. That lender's reputation can push your offer above others, even if the other buyer offered slightly more.
Local Lender vs. Online Lender: Which Wins in Denver?
This question comes up often. Online lenders advertise aggressively. Their rates can look attractive. So when should you choose a local Colorado specialist instead?
Factor | Local / Colorado Lender | Online / National Lender |
|---|---|---|
Contract knowledge | Knows CO deadlines | Often unfamiliar |
Agent relationships | Trusted by local agents | Unknown to local agents |
Closing speed | Can hit 21-day close | Often 30–45+ days |
Pre-approval strength | Underwritten upfront | Often just a soft pull |
Rate competitiveness | Very competitive | Sometimes a lower teaser rate |
Responsiveness | Local contact, fast response | Call center, slower escalation |
For competitive Denver metro markets, especially Castle Rock, a local expert almost always wins on the factors that matter most to sellers.
Colorado Mortgage Broker vs. Bank: What Buyers Should Know
Another common question: should you go to a bank or work with a Colorado mortgage broker?
A bank offers one set of products. Their underwriters and guidelines are in-house. They can be fast, but they may not have the best rate or program for your situation.
A Colorado mortgage broker shops multiple wholesale lenders. They can often find lower rates, better terms, and specialty programs, especially for self-employed buyers, investors, or those with complex income. The right choice depends on your profile. Ask yourself: Do I need flexibility in loan products? Or do I just want the simplest path with a lender I already know?
Pre-Approval Speed: Why It Can Win or Lose Your Offer
In Colorado, sellers often won't look at offers without a pre-approval letter. But not all pre-approvals are equal.
There are two main types:
Pre-qualification: A quick estimate based on what you say. No verification. Low value in a competitive market.
Full pre-approval: Income verified, credit pulled, assets reviewed. This is what Castle Rock sellers and agents want to see.
A strong mortgage pre-approval in Colorado tells the seller that your financing is real. It signals that you will not fall apart at the last minute. That confidence can tip a close decision in your favor. Some lenders can issue a verified pre-approval letter in 24–48 hours. Others take a week. Ask upfront: "How fast can you issue a full pre-approval if I need to move quickly?"
Questions to Ask Every Lender Before You Commit
Use this checklist when you compare home financing options in the Denver area. These questions separate real lenders from those who will slow you down.
What is your average closing time in the Denver and Douglas County area?
Do you verify income before the offer, or after?
Are you familiar with Colorado RECC contracts and their deadlines?
What is your all-in APR, not just the advertised rate?
Can you provide references from Denver or Castle Rock listing agents?
What happens if there is a delay on your end? Who is accountable?
Check Lender Reputation, Especially in Suburban Markets
Here is how to check a lender's reputation properly:
Step 1: Search "[Lender Name] + Denver reviews" on Google. Read the one- and two-star reviews first. Happy clients rarely write reviews. Unhappy ones always do. Pay close attention to complaints about communication delays and last-minute surprises.
Step 2: Ask your real estate agent. Experienced Denver agents keep a mental list of lenders who perform and lenders who create chaos. That insight is priceless.
Step 3: Look up the lender's NMLS license on the NMLS Consumer Access portal at nmlsconsumeraccess.org. Check for complaints, disciplinary actions, or license gaps. This takes five minutes and can save you enormous trouble.
Step 4: Ask the lender for three recent client references in the Denver area. A confident lender hands these over without hesitation. A reluctant one is a warning sign.
A Licensed Colorado Expert: Shereen Muckerman at NEXA Mortgage
When you want proof of what a strong lender reputation looks like, Shereen Muckerman is a solid example. She is a Certified Mortgage Advisor with NEXA Mortgage, LLC, and is actively licensed in Colorado.
Shereen holds a Certified Mortgage Consultant designation through MBS Highway and brings over a decade of experience across multiple lenders, including CrossCountry Mortgage, Highlands Residential Mortgage, and Neighborhood Loans. That background means she has seen how different lender systems perform under pressure.
She is licensed not only in Colorado but also in California, Florida, Texas, Oregon, Washington, and other states. That multistate reach is a sign of a serious professional, not a part-time originator. Beyond credentials, Shereen's focus is on client education. She works with first-time buyers, repeat buyers, and investors alike. Her goal is to make sure clients understand their loan, not just sign for it.
You can reach her directly at 720-501-8971 or by email at [email protected]. This is the kind of direct access that matters when you are in a fast-moving Castle Rock multiple-offer situation.
Ready to Win Your Next Offer?
Stop guessing which lender is actually right for you. Get a real answer, fast.
Castle Rock homes move quickly. Denver buyers who wait lose deals. Do not let a slow pre-approval or an unknown lender cost you the home you want.
Shereen Muckerman gives you verified pre-approvals, 21-day closing capability, and a team that knows Colorado contracts inside and out. Your offer deserves the strongest possible lender behind it. One call is all it takes to find out if you are truly ready to compete.
Visit us now at www.youwontbeatmyrate.com, and let us prove it.
Frequently Asked Questions
Q1. How do I compare mortgage lenders in Denver?
Start with four things: the real APR (not just the advertised rate), their average closing time in Denver, whether they verify your income upfront, and their reputation with local listing agents. A lender who checks all four boxes will serve you far better than one who only wins on rate.
Q2. What makes a mortgage lender the best fit for a Denver buyer?
The best Denver mortgage lender knows Colorado contracts, can close in 21 days when needed, issues fully verified pre-approvals, and has strong relationships with listing agents across the metro area, including Castle Rock, Parker, and Aurora.
Q4. Should I use a local lender or an online lender in Denver?
For competitive Denver markets, a local Colorado lender almost always wins where it counts most. Local lenders know Colorado contract deadlines, have relationships with Denver and Castle Rock listing agents, and can close faster. Online lenders may offer lower teaser rates, but they often struggle with Colorado-specific timelines.
Q5. How fast should a Colorado mortgage lender issue a pre-approval?
A strong lender can issue a fully verified pre-approval in 24–48 hours. If a lender says it takes a week or more, that is a red flag in Colorado's market. Denver and Castle Rock deals move quickly. You need a lender who can move with you.
Q6. What is the difference between a pre-qualification and a pre-approval in Colorado?
Pre-qualification is a quick estimate based on what you tell the lender, with no verification. Pre-approval means your income, assets, and credit have been verified. Colorado listing agents and sellers strongly prefer fully verified pre-approvals. In Castle Rock's competitive market, a pre-qual often isn't enough to get your offer accepted.
Q7. What is the difference between a Colorado mortgage broker and a bank?
A bank offers only its own loan products and uses its own underwriting guidelines. A Colorado mortgage broker shops multiple wholesale lenders to find the best rate and program for your specific situation. Brokers often access lower wholesale rates that banks cannot offer directly to consumers.


