Should You Buy a Home in Denver Now or Wait? 2026 Market Insight
Should You Buy a Home in Denver Now or Wait? 2026 Market Insight
Read the complete blog post below.
Timing the housing market sounds simple until you're the one making the decision. Buy now, and prices could rise. Wait, rates could fall, or prices could rise while you're sitting on the sidelines.
That's the challenge facing Denver homebuyers in 2026. The market has cooled from its earlier highs, but it hasn't collapsed. Mortgage rates remain higher than many buyers would like, while increased inventory has given buyers more room to negotiate. Meanwhile, areas such as Castle Rock and Douglas County are seeing their own changes in home prices, new construction, and demand.
So, should you buy a home in Denver in 2026 or wait? Let's look at the numbers and local market factors to help you decide.
Where the Denver Market Actually Stands in 2026
A few numbers worth knowing before you do anything else:
Median home price across the Denver metro is sitting in the high-$500,000s to low-$600,000s, depending on the month and property type. Prices have been essentially flat to slightly down year-over-year in several segments; this is not the double-digit-appreciation market of 2020–2021.
Inventory is up. Active listings have grown compared to the past few years, homes are sitting on the market longer, and seller concessions (covering closing costs, rate buydowns) are far more common than they were even 18 months ago.
Mortgage rates are hovering in the mid-to-high 6% range for a 30-year fixed loan. That's meaningfully higher than pandemic-era lows, but it's also been roughly stable for a while; no one is confidently predicting a return to 3-4% rates.
Rents have cooled too. Two-bedroom apartments in Denver are running in the high-$1,000s to low-$2,000s a month, which means the monthly gap between renting and owning has narrowed but hasn't disappeared.
Put together, that's a market economists are calling "buyer-favorable" for the first time in years, not because homes are cheap, but because buyers finally have room to negotiate, time to think, and options to choose from.
Denver Home Prices Forecast: What Comes Next
So what's the Denver home prices forecast for the rest of 2026 and beyond? Most local experts agree on one thing: don't expect a crash. Analysts expect steady, moderate growth instead of a sharp swing in either direction. Many forecasts point to a Denver appreciation rate of 3% to 5% each year. That's a healthy pace. It's also far slower than the double-digit jumps Denver saw a few years back.
This matters for your decision. A market that grows slowly gives you time. You don't have to rush in fear of missing out. At the same time, waiting years for prices to drop sharply may not pay off either.
Mortgage Rate Forecast 2026: Will Rates Drop Soon?
Rates are the other half of the equation. As of now, the 30-year fixed rate sits around 6.5% to 6.8%. That's higher than the 3% rates from 2021. But it has also been fairly stable for months. The mortgage rate forecast for 2026 points to rates staying in a similar range through the year. Some experts expect one or two small rate cuts if inflation cools. But no one is predicting a return to pandemic-era lows anytime soon.
Here's why that matters. If you wait for a big rate drop, you might be waiting a long time. Meanwhile, home prices could keep climbing. A future refinance is always possible if rates fall later. Buying today and refinancing tomorrow is a real strategy many buyers use.
Denver Real Estate Inventory 2026: Why Supply Still Feels Tight
You'd think more homes for sale would fix affordability. But Denver real estate inventory 2026 numbers tell a more complex story. Inventory has grown compared to the past few years. That's good news for buyers. Still, supply hasn't exploded the way some expected. Here's the reason.
Many current homeowners locked in mortgage rates near 3% back in 2020 and 2021. Selling now would mean trading that low rate for one twice as high. So a lot of owners are choosing to stay put. Some are even renting out homes they've outgrown instead of selling them. This is often called the lock-in effect. It keeps resale inventory tighter than normal, even in a slower market. Builders have noticed too. That's part of why new construction has picked up in growth areas outside the city center.
Wait to Buy or Buy Now in Colorado? The Real Framework
This is the question everyone asks. Should you wait to buy or buy now in Colorado? The honest answer depends on one thing more than any other: how long you plan to stay.
Buying a home costs money upfront. Closing costs alone can run 2% to 5% of the purchase price. Selling later adds more costs, including agent fees. Those costs only make sense if you own the home long enough to offset them.
Use this simple guide:
Staying 1 to 2 years? Renting is usually the smarter move.
Staying 3 to 4 years? This is a gray area. Run your numbers carefully before deciding.
Staying 5 years or more? Buying usually wins. You'll have time to build equity and ride out any price swings.
This single factor matters more than trying to time the market perfectly. Nobody can predict rates or prices with certainty. But you can know your own plans.
Castle Rock Home Value Growth and Douglas County's New Construction Boom
If you're looking south of Denver, the story shifts a bit. Castle Rock home value growth has cooled slightly this year, with typical values down modestly from last year's peak. That gives buyers a little more room to negotiate than existed during the frenzy of 2022 and 2023.
Douglas County remains one of the fastest-growing counties in Colorado. Strong schools, steady job growth, and easy access to the Denver Tech Center keep demand solid here.
This is also where new construction in Douglas County, Colorado, really shines. Because resale inventory stays tight, more buyers are turning to new builds instead. Communities like Terrain, Crystal Valley Ranch, Macanta, and The Canyons offer fresh options with active builder incentives.
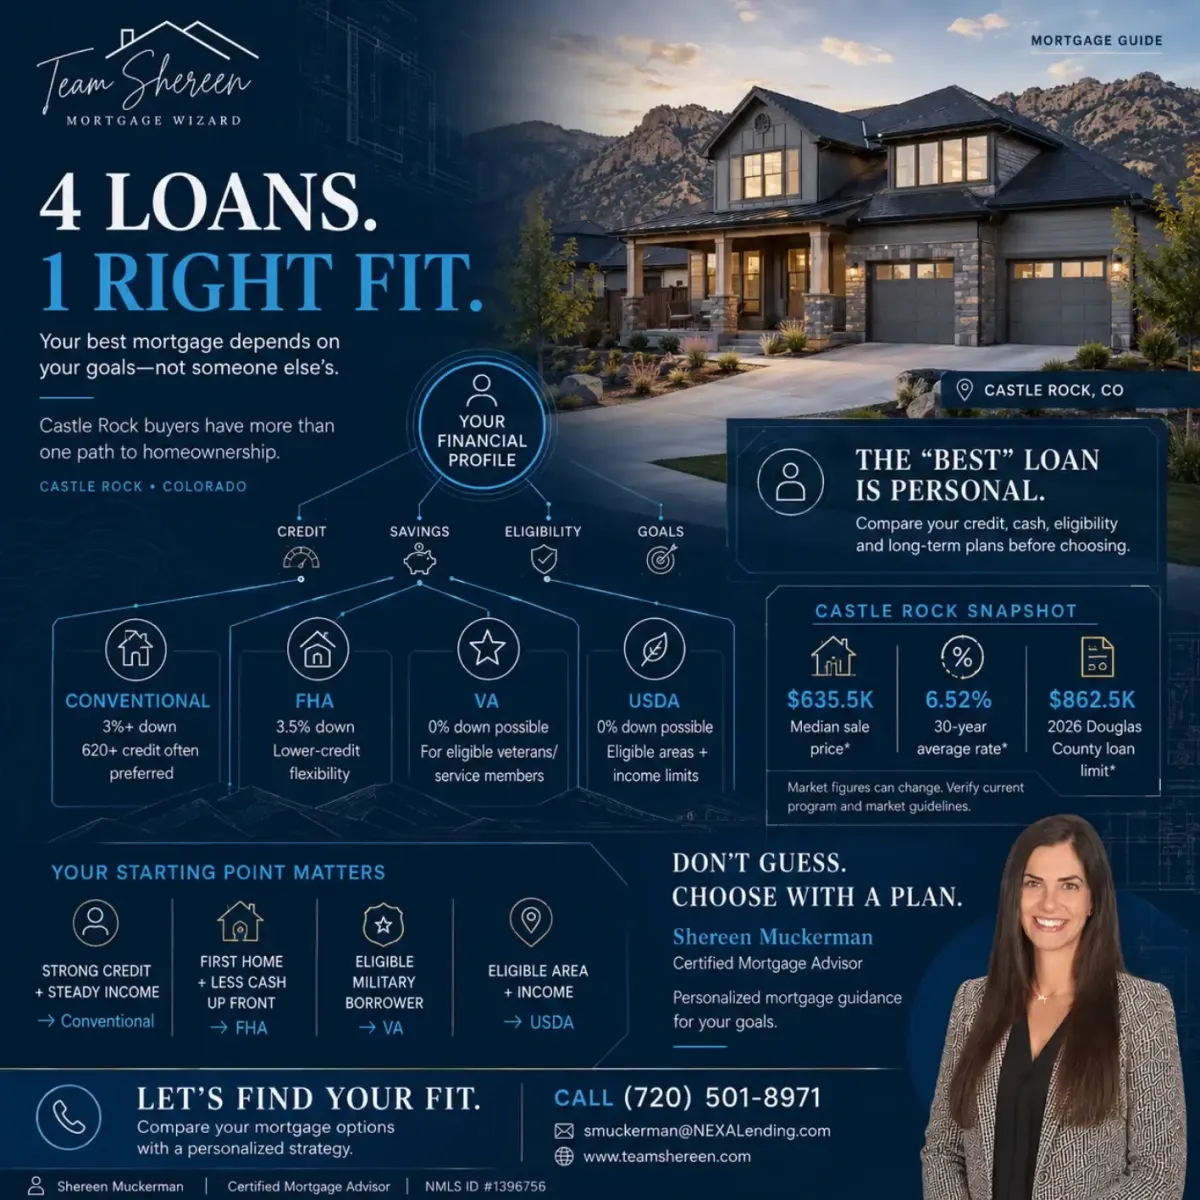
Veterans should take note here too. VA loans work with no loan limit for buyers with full entitlement in Douglas County. That opens doors that might otherwise feel out of reach.
Things Every Denver Buyer Should Check Before Signing
Beyond price and rate, a few Colorado-specific details deserve your attention.
HOAs are everywhere here. Colorado has one of the highest rates of homes inside community associations in the country. Before you buy, read the HOA rules closely. Ask about reserve funds too. A well-run HOA protects your home value. A poorly funded one can mean surprise bills down the road.
Insurance costs have climbed. Hailstorms and wildfire risk have pushed homeowners insurance prices up sharply across Colorado in recent years. Before you fall in love with a house, call an insurer first. Ask what coverage will actually cost in that specific neighborhood.
Not every slow-selling home has a problem. A home sitting on the market for a few weeks isn't automatically a red flag anymore. Right now, that's often just normal pacing, not a warning sign.
Programs That Can Make Buying Easier
Colorado offers real help for buyers who qualify.
First-time buyers can look into CHFA and metroDPA programs. These can lower the cash you need at closing. Combined with low-down-payment conventional loans, they open the door for many buyers who thought they needed 20% down.
Veterans and active military members should strongly consider a VA loan. It allows $0 down and skips mortgage insurance completely. VA rates also tend to run slightly below standard rates.
Investors have options too. DSCR loans qualify you based on a property's rental income, not your personal income. That can open doors that traditional loans keep closed.
If new construction in Douglas County, Colorado, interests you, ask your lender about builder incentives paired with these programs. The combination can lower your costs more than you expect.
So, Should You Buy a Home in Denver in 2026?
Here's the bottom line for the Denver housing market in 2026. There's no universal yes or no answer until you’ve had a consultation with Shereen Muckerman. But the pieces are clearer than they seem.
Rates have stabilized, even if they're higher than a few years ago. Prices are growing at a healthy, sustainable pace instead of spiking. Inventory has improved, giving buyers real negotiating room for the first time in years. A steady Denver appreciation rate also means your equity likely grows over time, even in a calm market. And Colorado-specific programs can make the numbers work better than you'd expect.
The real question isn't about the market. It's about your own timeline, your budget, and your goals. Once you know those, the market data becomes a tool instead of a source of stress. Whether you buy a home in Denver in 2026 or wait a little longer, knowing your numbers matters most.
Final Thoughts
There may not be a perfect moment to buy a home in Denver, and that is okay. What really matters is whether the timing, the price, and the payment make sense for your life right now. If your finances are in a good place, you plan to stay for a few years, and the monthly payment feels comfortable, buying now could be the right move for you.
Not sure where you stand? Shereen Muckerman can help you understand your mortgage options, monthly payment, and what buying in 2026 could look like for you. You'll learn about current rates, loan programs, and down payment options made for your situation. There's no pressure and no cost, just clear answers you can trust. Reach out to Shereen Muckerman now and take the first confident step toward your Denver home.


