Atlanta Investment Property Guide: Zoning and Financing
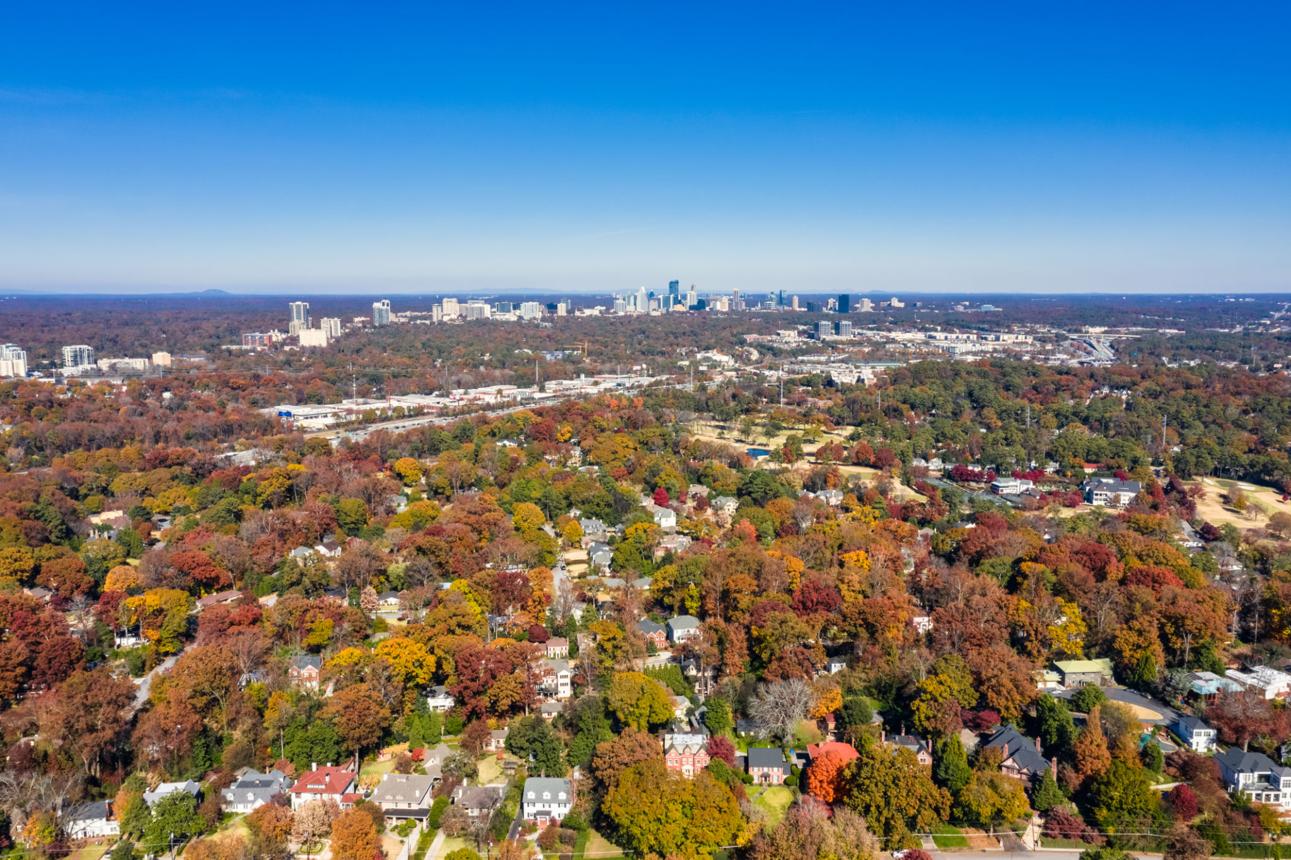
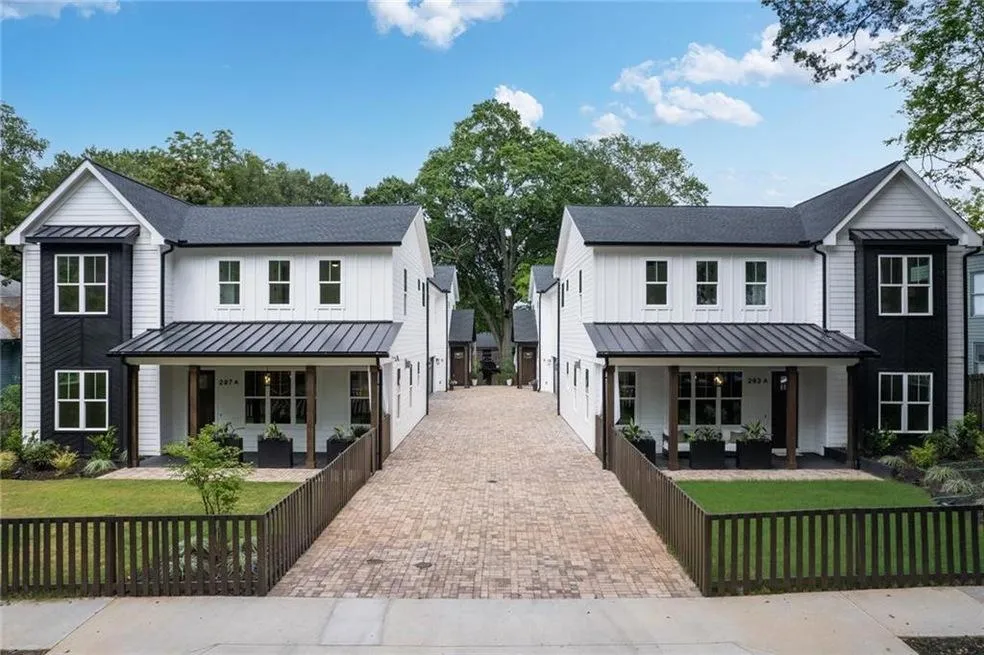
A successful real estate investment starts long before you find the property. It starts with a financial plan. Atlanta, Georgia, offers opportunities for investors interested in single-family rentals, multifamily properties, fix-and-flips, BRRRR projects, short-term rentals, and specialized housing.
But buying an investment property isn't simply about finding a good deal and getting approved for a loan. It's about making sure the property fits your financial position, your investment goals, the local zoning regulations, and your eventual exit strategy. One of the biggest mistakes I see investors make is finding a property first and figuring out the financing afterward.
That's backwards.
I recommend connecting with me twice during your investment process: once before you begin searching, and again when you've identified a property you're considering purchasing. The first conversation establishes your financial plan. The second evaluates the actual property, financing, projected returns, and exit strategy.
This is especially important when you're using hard money, renovating a property, or planning to refinance after improvements. My goal isn't simply to close your loan and collect a commission. I want to help you make informed financing decisions that support a profitable, sustainable investment portfolio.
1. First Step: Talk to Me Before You Start Looking at Properties
Before you contact a real estate agent, start browsing investment listings, or make an offer, let's have a conversation. I want to understand where you are financially, what you're trying to accomplish, and what financing options are available to you. This initial discovery call is where we build your investment financing plan.
We'll review your credit profile, liquidity, available reserves, experience, income or qualifying rental-income strategy, and the amount of capital you're comfortable investing. We'll also discuss what you want your portfolio to look like.
Are you purchasing your first investment property? Trying to acquire five rentals this year? Planning to use the BRRRR method? Looking for a renovation project that can generate cash for your next purchase? Your answers help us determine the types of properties and financing structures that may work for you.
What we'll establish during your first call
Your realistic purchase-price range and available down payment.
Financing options based on your credit, experience, and financial position.
How much cash you should retain for reserves, repairs, and unexpected expenses.
Whether conventional, DSCR, hard-money, renovation, or portfolio financing may be appropriate.
Your preferred property type, rental strategy, and investment criteria.
Your cash-flow and return-on-investment targets.
Potential limitations involving property condition, loan-to-value, credit, or lender guidelines.
The goal is to give you a financially realistic buy box before you start shopping. That way, you're not wasting time pursuing properties that don't fit your financing strategy.
2. Second Step: Found a Property? Let's Review the Deal Before You Commit
Once you've identified a property, it's time for our second conversation. This is where we move from the overall financial plan to evaluating the specific investment.
I want to know the purchase price, property condition, expected renovation costs, current or projected rents, after-repair value, and your intended exit strategy. We also need to consider zoning, occupancy, insurance, and any unusual property characteristics that could affect financing.
The Two-Call Investor Strategy
Call 1: Before you shop: Create your financial plan, establish your buy box, understand financing options, and identify potential roadblocks.
Call 2: Before you commit: Review the actual property, projected returns, loan structure, renovation budget, short- and long-term goals, and exit strategy.
For hard-money and rehab deals, we also review the proposed refinance or sale before the initial financing is finalized.
Why this is critical for hard-money and rehab projects
Hard-money loans can be useful tools for investors purchasing distressed properties or completing renovations. But they also create risks that need to be understood before closing. A short-term loan may have higher rates, origination points, draw fees, extension fees, and a maturity date that comes much sooner than a traditional mortgage.
If your exit strategy is to refinance into a DSCR loan after completing renovations, I want to evaluate that refinance before you take out the hard-money loan. We need to know whether the proposed refinance lender will accept the property's condition, projected rent, appraisal value, title seasoning, and loan-to-value structure.
What happens if the appraisal comes in lower than expected?
What if renovations take three months longer?
What if the DSCR lender requires more equity than you anticipated?
I don't want you six months into a project discovering that the refinance you were counting on isn't available. We can't eliminate every investment risk, but we can identify many financing-related issues before you purchase.
3. Understanding Atlanta's Zoning Laws Before Purchasing
Atlanta's zoning code is especially important for investors considering duplexes, multifamily properties, room rentals, short-term rentals, and group housing. The City of Atlanta uses several residential zoning classifications, including single-family districts, two-family districts, residential general districts, and multifamily districts. These designations affect which uses are allowed and whether you can add units, convert a property, or operate a specialized rental business.
Atlanta zoning districts investors should understand
Zoning district | General classification | Investment considerations |
R-1, R-2, R-3 | Single-family residential | Traditional single-family rentals and applicable accessory uses |
R-4, R-4A, R-4B | Single-family residential | Rental homes, renovations, potential accessory units subject to specific rules |
R-5 | Two-family residential | Duplex opportunities and qualifying residential configurations |
RG districts | Residential General | Potentially broader residential building types and density |
MR districts | Multifamily residential | Multifamily buildings and higher-density residential development |
PD districts | Planned development | Site-specific permitted uses and development standards |
SPI districts | Special Public Interest | Additional area-specific development requirements |
Atlanta's R-3 and R-4A regulations expressly identify single-family detached dwellings as permitted principal uses, with short-term rentals subject to separate city rules.
Municode Library
Multifamily and specialized residential uses require careful review. For example, the MR district regulations address personal care homes, assisted living facilities, and rehabilitation centers through special-use permit provisions.
Municode Library
Don't assume that because a property has six bedrooms, it can legally operate as six separate rental units. Likewise, a property advertised as a duplex may have been converted without the required approvals. Before purchasing, verify the legal number of dwelling units, applicable zoning district, permits, and intended use.
4. Atlanta Zoning Map: Where Are the Different Investment Zones?
Atlanta provides an official interactive zoning map that allows investors to search by address, parcel, or zoning classification.
Official City of Atlanta Zoning Map
City GIS
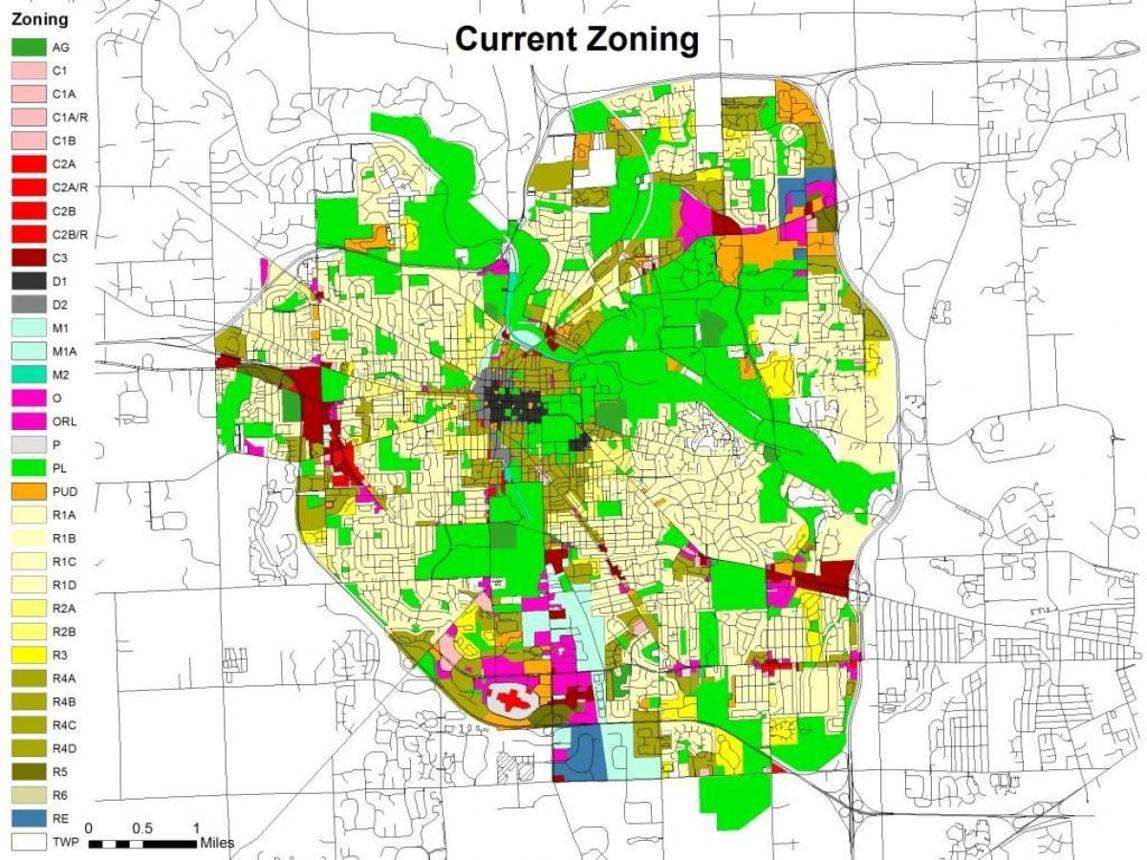
Explore Atlanta's Official Zoning Map. Illustrative zoning-map image. Use the official interactive GIS portal for verified zoning boundaries and property-specific information.
Atlanta GIS
Atlanta's GIS portal also provides access to official zoning-map PDFs, lot-boundary information, rezoning cases, and future land-use maps. The future land-use map can help you understand the city's long-range vision for an area, but it is not the same as current zoning and does not independently authorize a use.
Atlanta GIS
For investors, I recommend researching the property on the map before making an offer and obtaining written zoning clarification for any unusual proposed use.
5. Atlanta Neighborhoods Worth Evaluating
Different Atlanta neighborhoods can support different investment strategies, but the right location depends on your acquisition budget, property type, rental strategy, and expected returns.
West End
Older housing stock may provide renovation and long-term rental opportunities. Investors should evaluate historic protections, renovation costs, and the property's actual zoning.
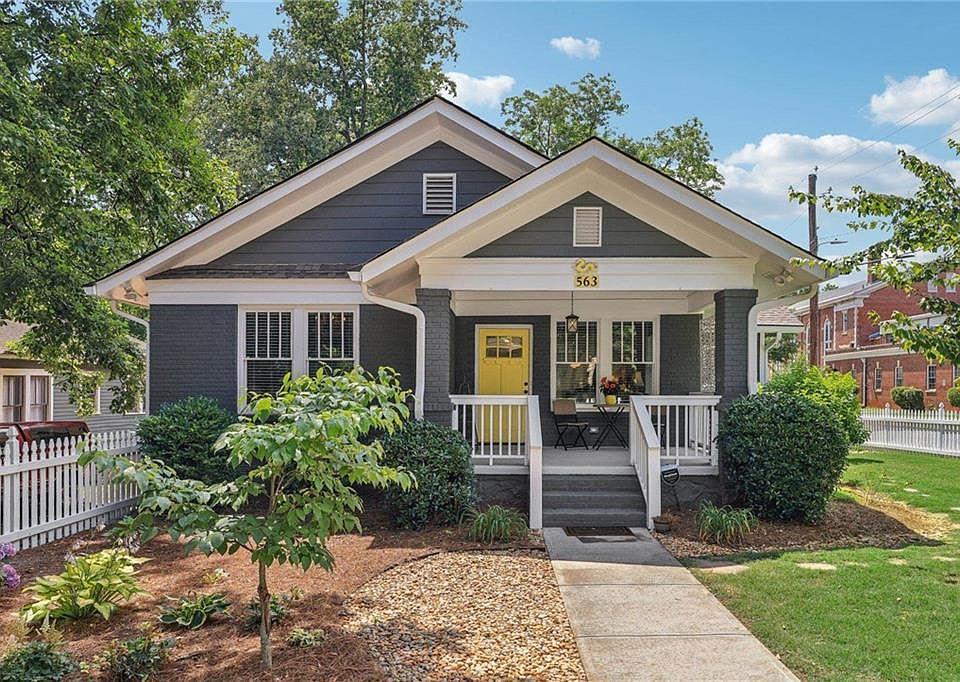
East Atlanta Village
Research established residential properties, potential renovations, and rental demand. Make sure the purchase price leaves room for expenses and a realistic return.
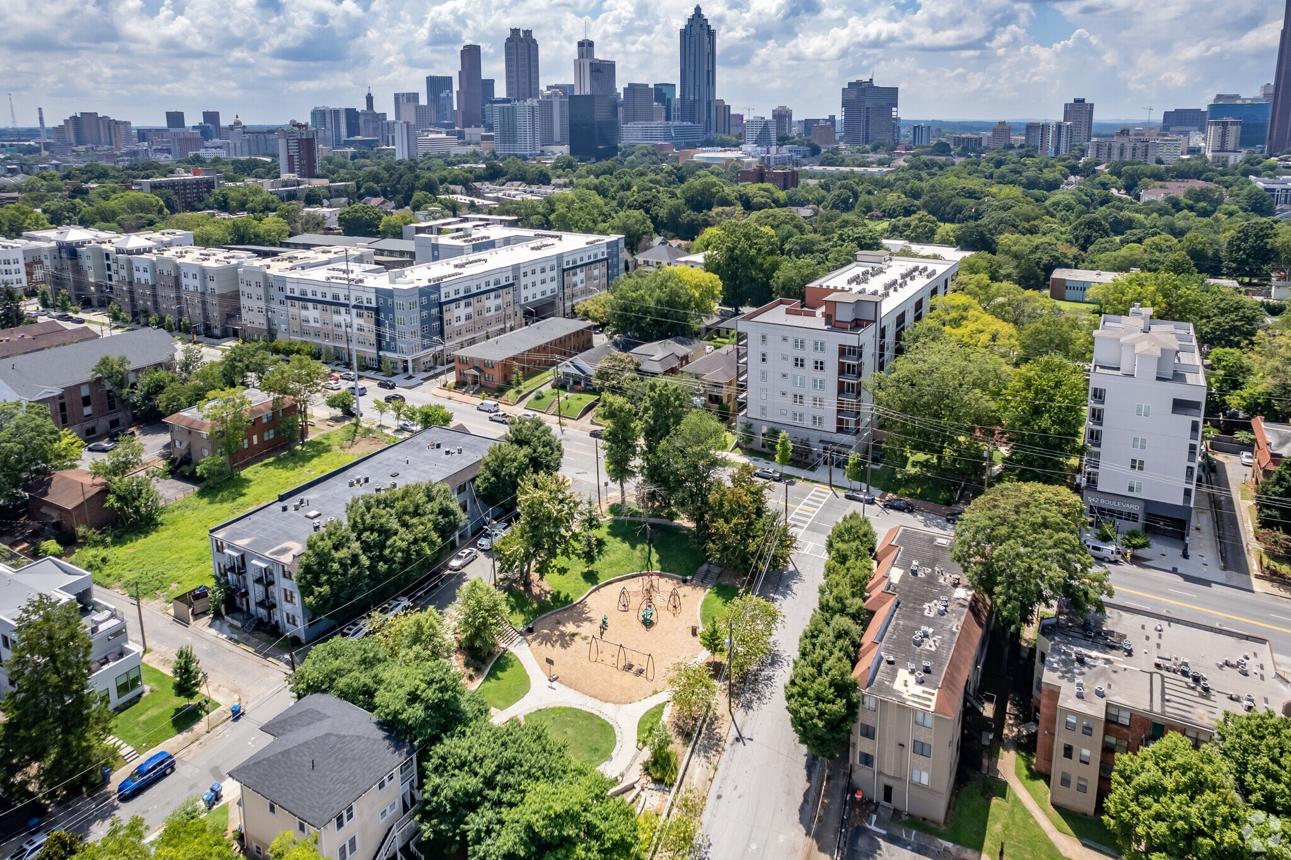
Old Fourth Ward
Evaluate townhomes, smaller multifamily properties, and proximity to employment and amenities. Higher acquisition costs can make cash-flow analysis particularly important.
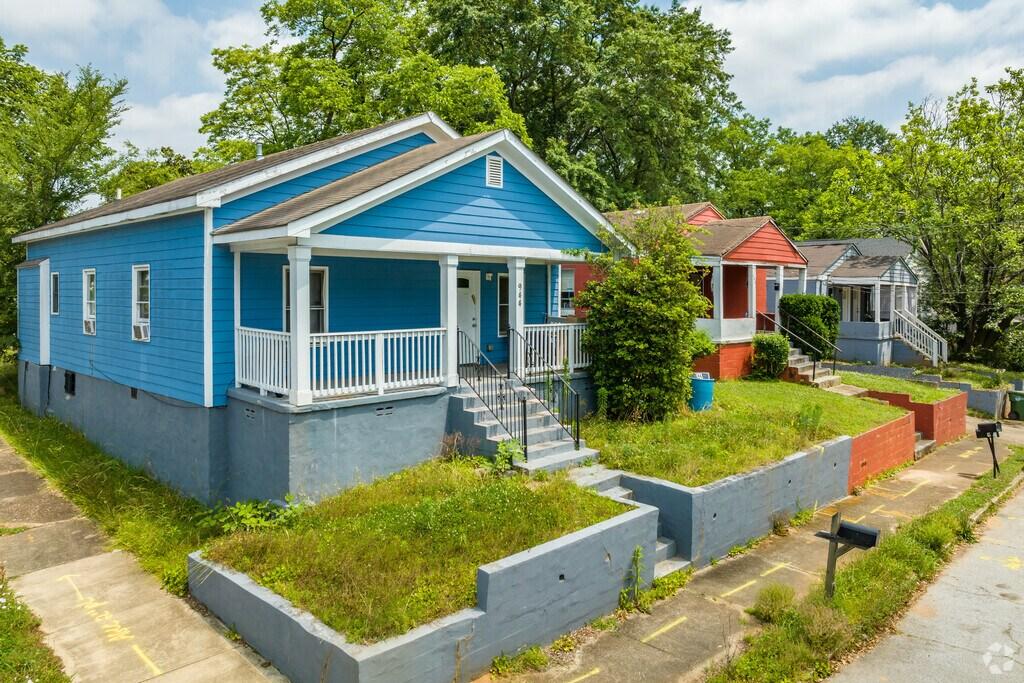
Pittsburgh
Investors researching renovations and value-add properties should carefully assess property condition, comparable sales, and rehabilitation budgets.
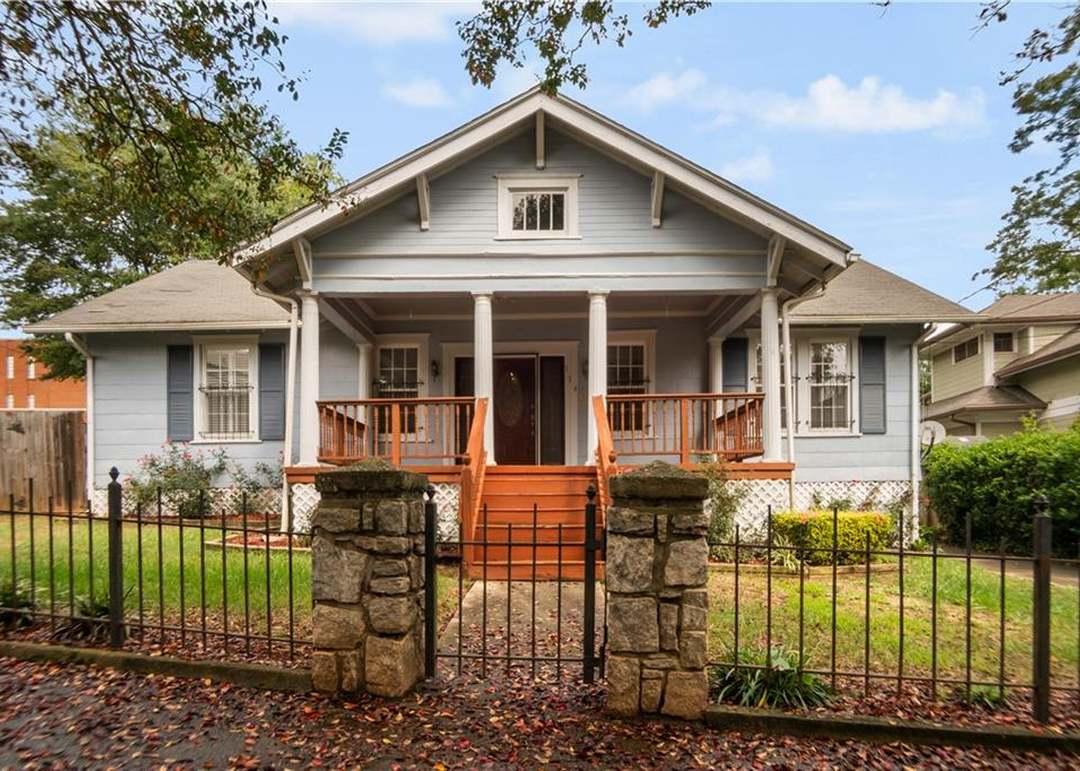
Decatur
Consider traditional rentals and proximity to employment and amenities, while recognizing that properties inside Decatur city limits are subject to a separate municipal zoning code. These areas are starting points for research, not claims that they currently provide the highest investment returns.
Geographic reference map
Neighborhood locations only. These pins do not represent zoning boundaries, investment ratings, or permitted property uses.
6. Short-Term Rentals, Room-by-Room Rentals, and Group Housing in Atlanta
This is where investors need to be especially careful. A property's projected income can look very different depending on whether you rent it to one household, multiple unrelated tenants, short-term guests, or a specialized housing operator.
Short-term rentals
Atlanta has a specific short-term rental licensing program. Under the city's published rules, an eligible owner or long-term tenant can apply for a license covering their primary residence and one additional dwelling unit. The primary residence must be registered first. The city requires a short-term rental license, and its ordinance lists a $150 annual application fee.
Municode Library
This is an important distinction for investors: Don't assume you can purchase multiple non-owner-occupied properties in Atlanta and automatically operate all of them as short-term rentals under the standard licensing arrangement.
Verify the proposed ownership and operating structure, licensing eligibility, HOA restrictions, and current rules before making an offer.
Room-by-room rentals and boarding houses
Renting a home by the bedroom may produce more gross income than a traditional rental, but it also introduces additional regulatory and financing considerations. Atlanta's Housing Code defines a rooming house as dwelling space with rooming units rented to five through fifteen people.
Section 26 contains additional requirements for rooming houses, boarding houses, and similar facilities, including permits and business licensing.
Municode Library
The housing-code definition does not itself establish that a rooming house is permitted in a particular zoning district. Before purchasing, confirm whether your intended arrangement is classified as ordinary household living, a rooming house, a boarding house, or another regulated use.
Also consider how your lender will evaluate the rental income. Some DSCR lenders may use traditional market rent rather than the sum of individual bedroom rents. Other lenders may consider specialized income structures with additional documentation.
Group homes, recovery housing, and personal care homes
Specialized housing investments can involve both local zoning regulations and Georgia state requirements.
Georgia regulates personal care homes under Rule 111-8-62 and community living arrangements under Rule 290-9-37. These regulations contain specific definitions, licensing provisions, and exemptions.
Subject 111-8-62 PERSONAL CARE HOMES
+1
Not every sober living home or shared residence falls under the same category. Depending on the arrangement, you may need to evaluate licensing, resident services, fair-housing protections, building and fire safety, and insurance. If this is your investment strategy, obtain the appropriate zoning and legal review before committing to a property.
7. Run the Numbers Before You Buy
A property can look profitable based on projected rental income but become a poor investment once you account for operating expenses. I want investors to evaluate the actual numbers, including property taxes, insurance, vacancy, maintenance, management, financing costs, and capital reserves.
Don't confuse projected rent with actual cash flow
If a seller tells you the property can generate $3,000 per month, I want to know where that number came from. Is there a signed lease? A rental appraisal? Comparable properties? Or is it simply a projection? For short-term rentals, we may review data from services such as AirDNA, but we also need to consider seasonality, occupancy, management costs, cleaning, furnishings, and the property's performance as a long-term rental.
For room rentals, we need to confirm both legal use and whether the lender accepts that income. A property doesn't become a good investment just because the spreadsheet shows a positive number.
8. Hard-Money Loans, Rehab Financing, and the Exit Strategy
This is one of the most important parts of the investment process. Hard-money financing can help investors purchase distressed properties, complete renovations, and move quickly when traditional financing isn't suitable.
But it can also be expensive if the project doesn't go according to plan. Before taking out a hard-money loan, we should analyze the entire project, not just the purchase.
Example: Atlanta fix-and-flip
Item | Hypothetical amount |
Purchase price | $225,000 |
Renovation budget | $55,000 |
Acquisition closing costs | $6,000 |
Financing and holding costs | $20,000 |
Estimated selling costs | $24,000 |
Total projected costs | $330,000 |
After-repair value | $375,000 |
Projected profit before income taxes | $45,000 |
On paper, the project has a $45,000 projected profit. But what happens if the renovation costs increase by $15,000 and the property sells for $15,000 less than expected? Your projected profit drops to $15,000. That's why I want to review the financing and the exit strategy before you purchase.
What if you're planning to refinance instead of sell?
For BRRRR investors, the refinance is just as important as the acquisition. We need to know whether the proposed DSCR lender will recognize the new appraised value, what loan-to-value limits apply, whether title seasoning is required, and whether the rental income supports the new mortgage.
We also need to understand how much of your original capital you can realistically recover. I don't want you assuming you'll get all your money back simply because the property appraises for more after renovations. Before you take out a hard-money loan, let's evaluate the proposed permanent financing and establish a backup exit strategy.
9. Why Work With Shereen Muckerman, The Mortgage Wizard?
Here's something I want investors to understand:
You have a buy box. Lenders have a buy box, too. Your buy box might include properties under $300,000, a minimum cash-flow target, specific neighborhoods, or a particular renovation strategy.
Lenders also have criteria. One lender may be comfortable with traditional single-family rentals but unwilling to finance a manufactured home, rural property, or room-by-room rental. Another may offer specialized programs for renovation projects, short-term rentals, or investors with multiple properties.
When you go directly to one lender, you're trying to fit every deal into that lender's guidelines. If the deal doesn't fit, you're back to shopping. As a mortgage broker, that's my job. I shop the lenders for you.
Relationships with more than 50 lenders
I have relationships with over 50 lenders, giving me access to different financing programs, property guidelines, pricing structures, and investment loan options. I work to understand which lenders have an appetite for which types of deals.
I also keep up with guideline changes because a lender that was a great fit for your last investment may not be the best fit for your next one. I'm not simply looking for the lowest advertised rate. I'm looking for financing that fits your property, your financial position, and your investment goals.
Why I'm not an order taker
Sometimes an investor will text me:
"Can you do a 6.5% DSCR loan, no points, and low fees?"
I understand why investors ask. Everyone wants competitive financing. But I can't recommend the right loan without understanding the deal. What if the loan with the lowest rate has a five-year prepayment penalty, but you're planning to refinance in twelve months?
What if the lender won't accept the property's rental-income structure? What if a different financing option helps you preserve more capital for your next investment? The lowest interest rate isn't always the best financing strategy.
I want to understand your short-term and long-term goals, the property, your credit profile, and your exit strategy. That's how we determine which financing option makes sense.
One credit report, multiple lender options
One benefit of working with my team is that we generally obtain one mortgage credit report that can be used with participating lenders for up to 120 days, subject to their requirements. If we need to change lenders, we can often transfer the existing documents and continue the process without rebuilding the entire file. Some lenders may require updated information or a new credit report, but our goal is to minimize unnecessary delays.
Built for repeat investors
My business is built on repeat clients and referrals. When I work with an investor, I want to understand their financial profile, preferred investment criteria, and long-term goals. We maintain their file and update documents as needed for future transactions.
That way, when they find their next property, we're not starting from scratch. We review the deal, determine which lenders are a good fit, update the documentation, and move forward. I want to be the person you call before your next investment, not just when you need a loan.
10. What We Expect From Investors Working With Our Team
My team and I pride ourselves on client service. Our goal is to close eligible transactions within 30 days whenever the loan program and circumstances allow. To accomplish that, we need investors who are committed, responsive, and respectful of the process.
When we commit to your transaction, we're committing our time, expertise, and resources. We expect you to provide documentation promptly, communicate throughout the process, and meet agreed-upon deadlines. If you're still shopping lenders, that's fine. We encourage you to complete that process before asking us to begin full loan processing.
Once we move forward together, we expect timely communication. If communication stops, we may place the file on hold for one week, which can delay closing. If we're still unable to reach you, we may withdraw the application from active processing, subject to applicable notice and regulatory requirements.
These expectations help us maintain the same service standards for every client. We work best with investors who value professional guidance and are serious about building successful portfolios.
11. Atlanta Investment Property Due Diligence Checklist
Your investor checklist
Complete the first financing discovery call before property shopping
Establish purchase budget, reserves, and investor buy box
Verify property zoning through Atlanta GIS
Confirm legal unit count and intended rental use
Review historic overlays, permits, and property restrictions
Verify comparable rents and projected operating expenses
Obtain realistic insurance and property-tax estimates
Review rehab scope, contractor estimates, and contingency budget
Complete the second deal-review call before committing
Verify hard-money terms, draw schedule, fees, and maturity
Confirm refinance seasoning, DSCR, and LTV requirements
Establish primary and backup exit strategies
12. Final Thoughts: Your Investment Starts With a Financial Plan
Atlanta offers investors a wide variety of opportunities, but the right investment isn't simply the property with the best-looking numbers. It's the property that fits your financial plan, your financing options, your goals, and your exit strategy.
That's why I encourage investors to work with me at two critical points. First, before you start shopping. Let's establish your financial plan, understand your financing options, and define your buy box. Second, when you find a property. Let's review the actual deal, the financing, the cash flow, and the short-term and long-term exit strategies.
This is especially important when you're using hard money or planning a renovation and refinance. I don't want to be the lender you call at the last minute because you need a loan. I want to be part of your investment planning process.
My goal isn't just to get you to the closing table. It's to help you make informed financing decisions that support a profitable portfolio you'll want to keep growing. And when you're ready for the next property, I want to be the first person you call.